Generation Mortgage: Why younger Australians face a very different retirement
November 2nd, 2026
A very different retirement awaits
For generations of Australians, owning the family home outright by retirement was almost taken for granted.
You bought a house during your working years, gradually paid down the mortgage and ideally entered retirement debt-free, with superannuation and the Age Pension available to help fund your lifestyle (or, if you were fortunate, an employer-sponsored defined benefit pension).
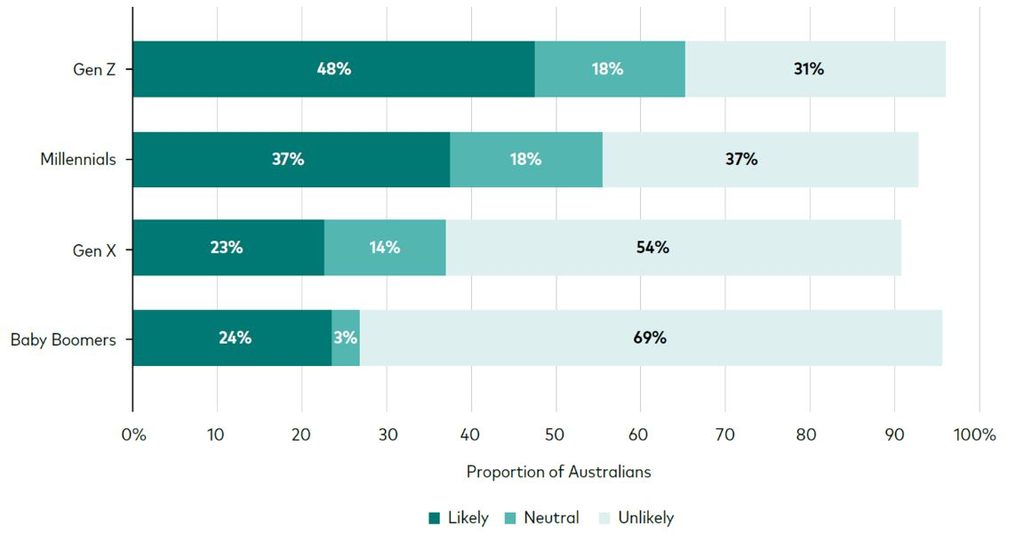
For many younger Australians, that same path is becoming increasingly difficult. Research reveals a generation expecting to work longer, carry substantially more housing debt into retirement and need considerably more income once they get there. Nearly half of Gen Z Australians (48%) surveyed expect to still have a mortgage in retirement, alongside more than one in three Millennials (37%) surveyed, while others expect to remain renters throughout retirement.
Self-assessed likelihood of retiring with a mortgage
Source: Vanguard’s How Australia Retires 2026 survey of more than 1,800 Australians. Results are based on survey responses and are intended for illustrative and informational purposes only.
Using super to pay off the mortgage
These shifts could fundamentally change how younger cohorts eventually fund their retirement. Of those expecting to retire with a mortgage:
39% are considering using some of their super to pay off their debt
16% expect to sell their property
45% plan to continue making mortgage repayments during retirement.
Daniel Shrimski, Vanguard’s Managing Director, Asia Pacific, says the findings demonstrate how much the path to retirement is changing.
“Australians are facing a tougher road to retirement than previous generations. Higher housing costs, bigger debts and cost-of-living pressures are changing what retirement looks like and what it will take to fund it,” he said.
Whether using superannuation savings to repay debt is appropriate will depend on individual circumstances and may impact retirement income. Individuals should consider seeking professional advice.
Younger Australians expect to retire later
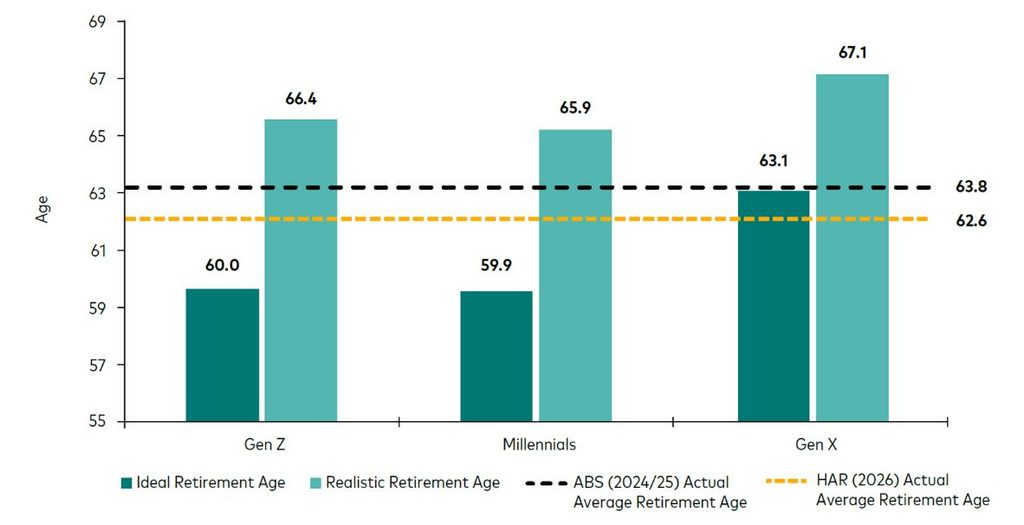
Housing isn’t the only thing changing. The research, based on a nationally representative survey of more than 1,800 Australian adults, found most working-age Australians now expect to retire at age 66 or 67. By comparison, Australians who are already retired reported leaving the workforce at an average age of 63.
Working-age Australians’ estimates of their ideal and realistic ages at retirement
Working an additional three or four years can have significant financial implications. It provides additional years of employment income and super contributions while delaying the point at which someone needs to begin relying on their retirement savings.
But for some Australians, working longer may increasingly be a necessity rather than a choice. The research suggests housing security is emerging as an important factor in retirement confidence, with younger generations facing the prospect of simultaneously funding their retirement lifestyle and continuing to meet housing costs.
The $90,000 retirement
Despite these pressures, Australians continue to have high expectations for life after work. The research found Australians aspire to an active retirement that includes remaining in their own home, travelling regularly and spending money on hobbies and their health. But younger Australians believe funding that lifestyle will require substantially more money.
Australians under 45 estimate they will need over $90,000 a year in retirement. By comparison, Australians aged 65 and over report needing around $60,000 a year.
Some of that difference may reflect the longer time younger Australians have before retirement and expectations that inflation will push up the cost of living. But it also illustrates the challenge ahead: younger Australians expect retirement to cost more while simultaneously anticipating entering it with greater housing expenses.
Planning remains a major gap
While retirement expectations are changing, one of the biggest opportunities identified by the research is surprisingly simple: having a plan. Despite compulsory superannuation, many Australians still don’t have a retirement plan.
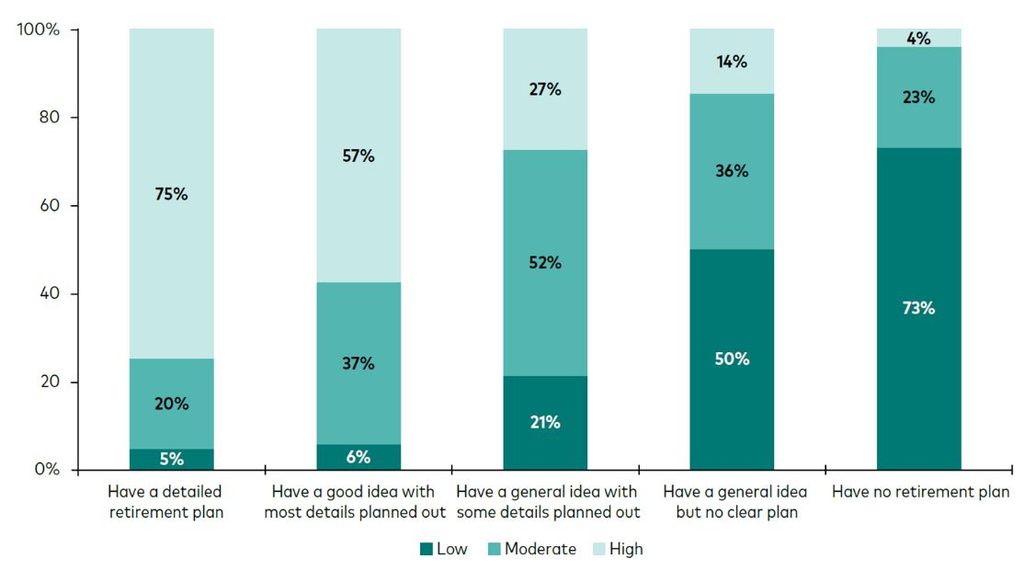
“While 45% of working-age Australians have no retirement plan, our research shows that people who have started planning for retirement are significantly more confident about their future,” Shrimski says.
The chart below shows how retirement confidence varies depending on the level of planning.
Retirement confidence by level of retirement planning
It doesn’t need to be complicated
A retirement plan doesn’t necessarily need to be complicated. It can start with a few basic questions, whether you’re thinking them through yourself or discussing them with your partner, family or friends:
When would you like to retire?
Where would you like to live?
What sort of lifestyle do you want?
How much super do you currently have?
Will you still have a mortgage?
How much income might you need?
Answering those questions may help identify the gap between where you are today and where you would like to be.
Small steps can make a difference
The good news is that retirement planning doesn’t need to happen all at once.
The research highlights several practical actions Australians can take to become more engaged with their financial future:
Build a retirement plan. Think about your future goals and the steps that could help you achieve them.
Understand how the retirement system works. Learn about superannuation and the role it can play alongside the Age Pension.
Improve your financial literacy. Build your understanding of basic financial concepts through reading, research and conversations.
Consider additional super contributions. Where your circumstances allow, extra contributions may help strengthen your retirement savings.
Check your super regularly. Aim to review your balance, contributions and investment options at least every six months.
As Shrimski puts it: “Our research shows that small actions taken consistently over time can build confidence and help Australians prepare for the retirement they want.”
For younger Australians facing higher housing costs, larger mortgages and potentially longer working lives, the retirement journey may look very different to the generations before them.
But the basic principle remains the same: the earlier you understand where you stand and where you want to go, the more options you may have to shape the retirement you ultimately experience.
This article is general in nature and has not been tailored to individual circumstances. Before acting on this information, you should assess your own circumstances or seek personal advice from a licensed financial adviser. This article is current as at the date of issue but may be subject to change or be superseded by future publications. While it is believed that the information is accurate and reliable, the accuracy of that information is not guaranteed in any way. Past performance is not a reliable indicator of future performance, and it should not be relied on for any investment decision. Whilst care has been taken in preparing the content, no liability is accepted by the Licensee nor any of its agents, employees or related bodies corporate for any errors or omissions in this publication, and/or losses or liabilities arising from any reliance on this information.
Certe is part of the AZNGA Group. General Advice Warning: The information provided on this webpage is intended to provide general information only and the information has been prepared without taking into account any particular person’s objectives, financial situation or needs. Before acting on such information, you should consider the appropriateness of the information having regard to your personal objectives, financial situation or needs. Certe Wealth Protection Pty Ltd (ABN: 31 150 270 278) is a Corporate Authorised Representative of Fortnum Private Wealth Ltd ABN 54 139 889 535 AFSL 357306.
Generation Mortgage: Why younger Australians face a very different retirement